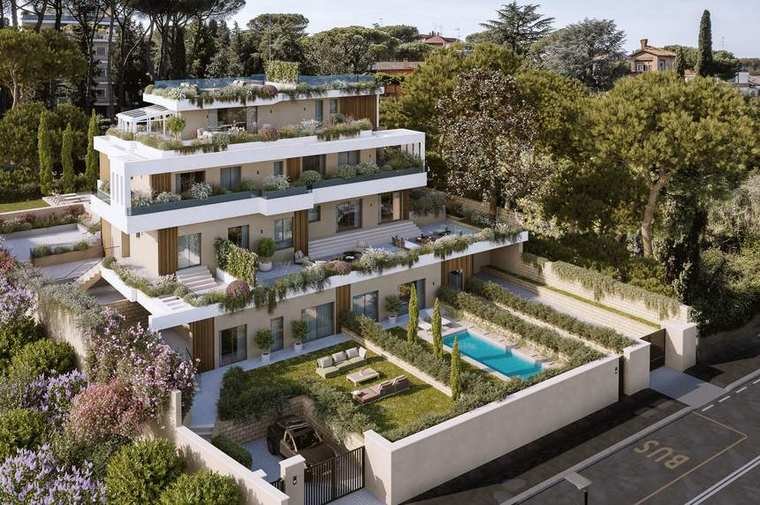
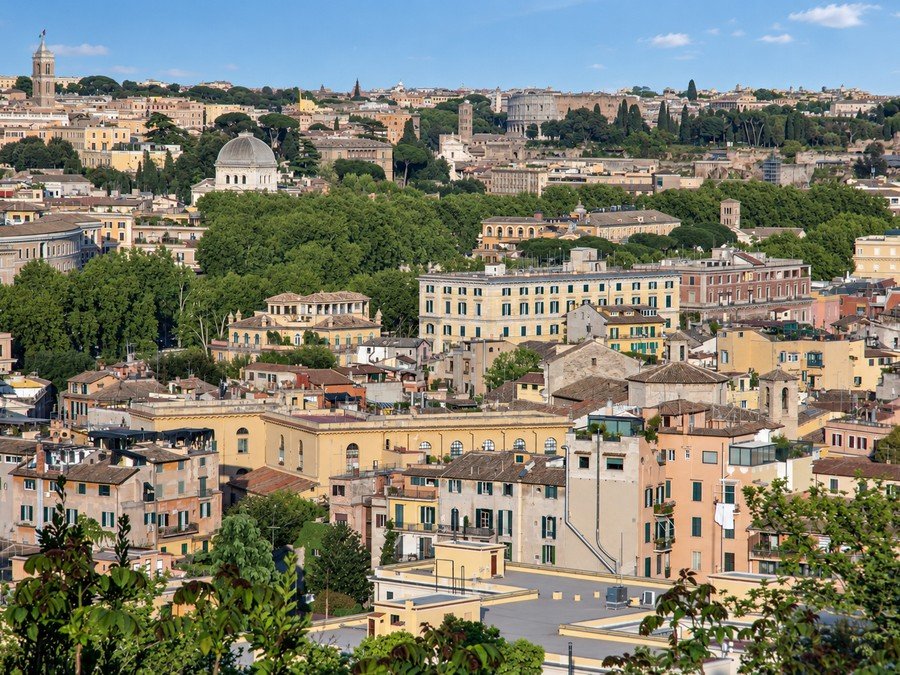
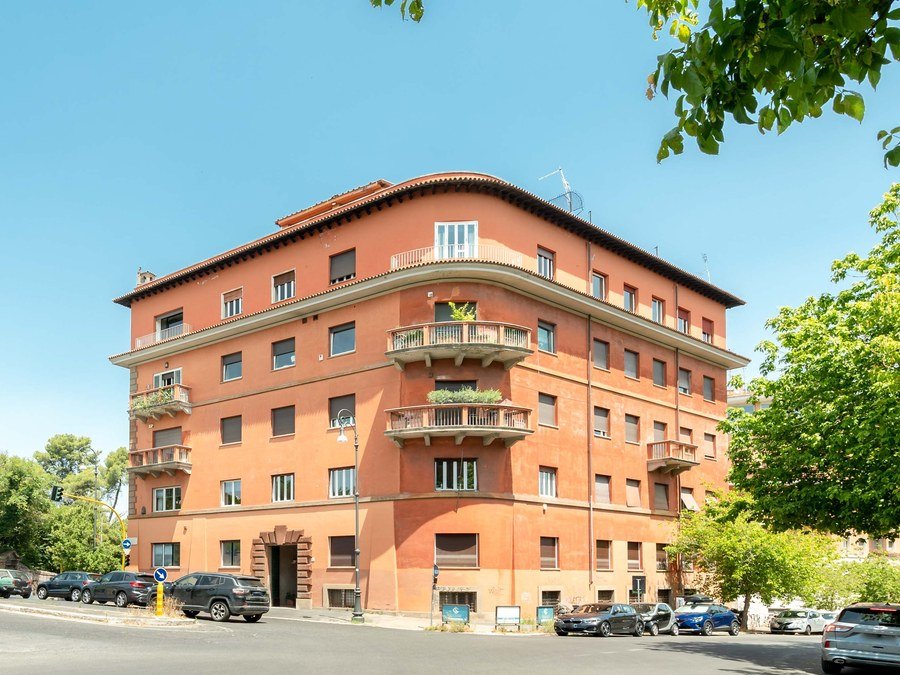
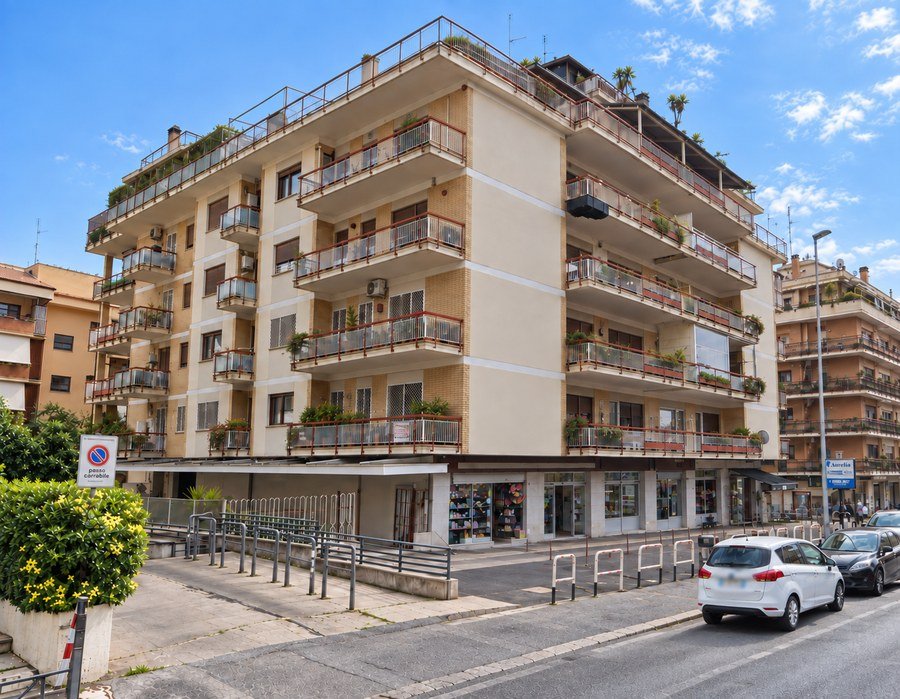
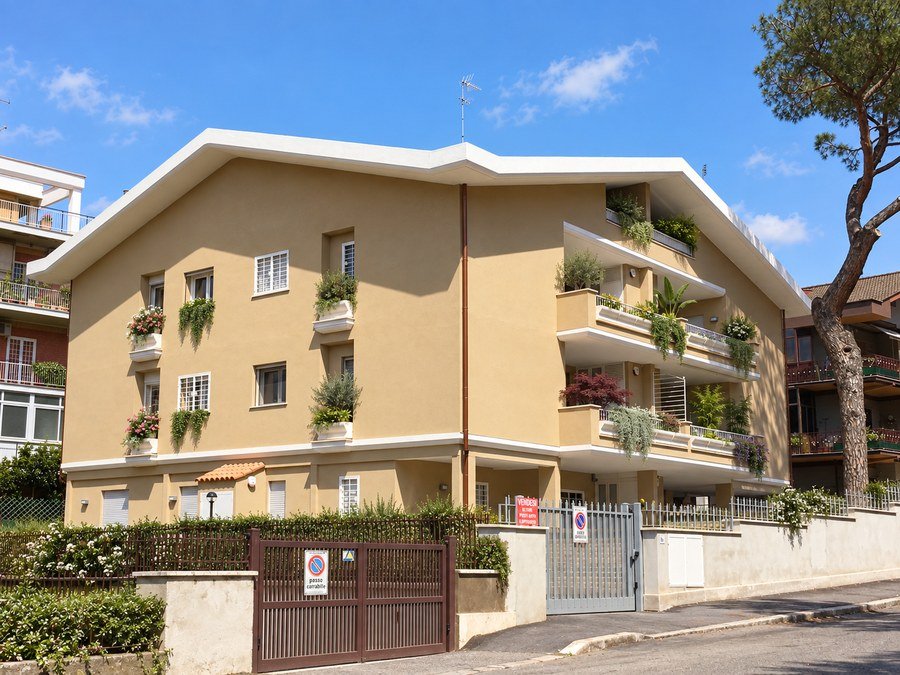
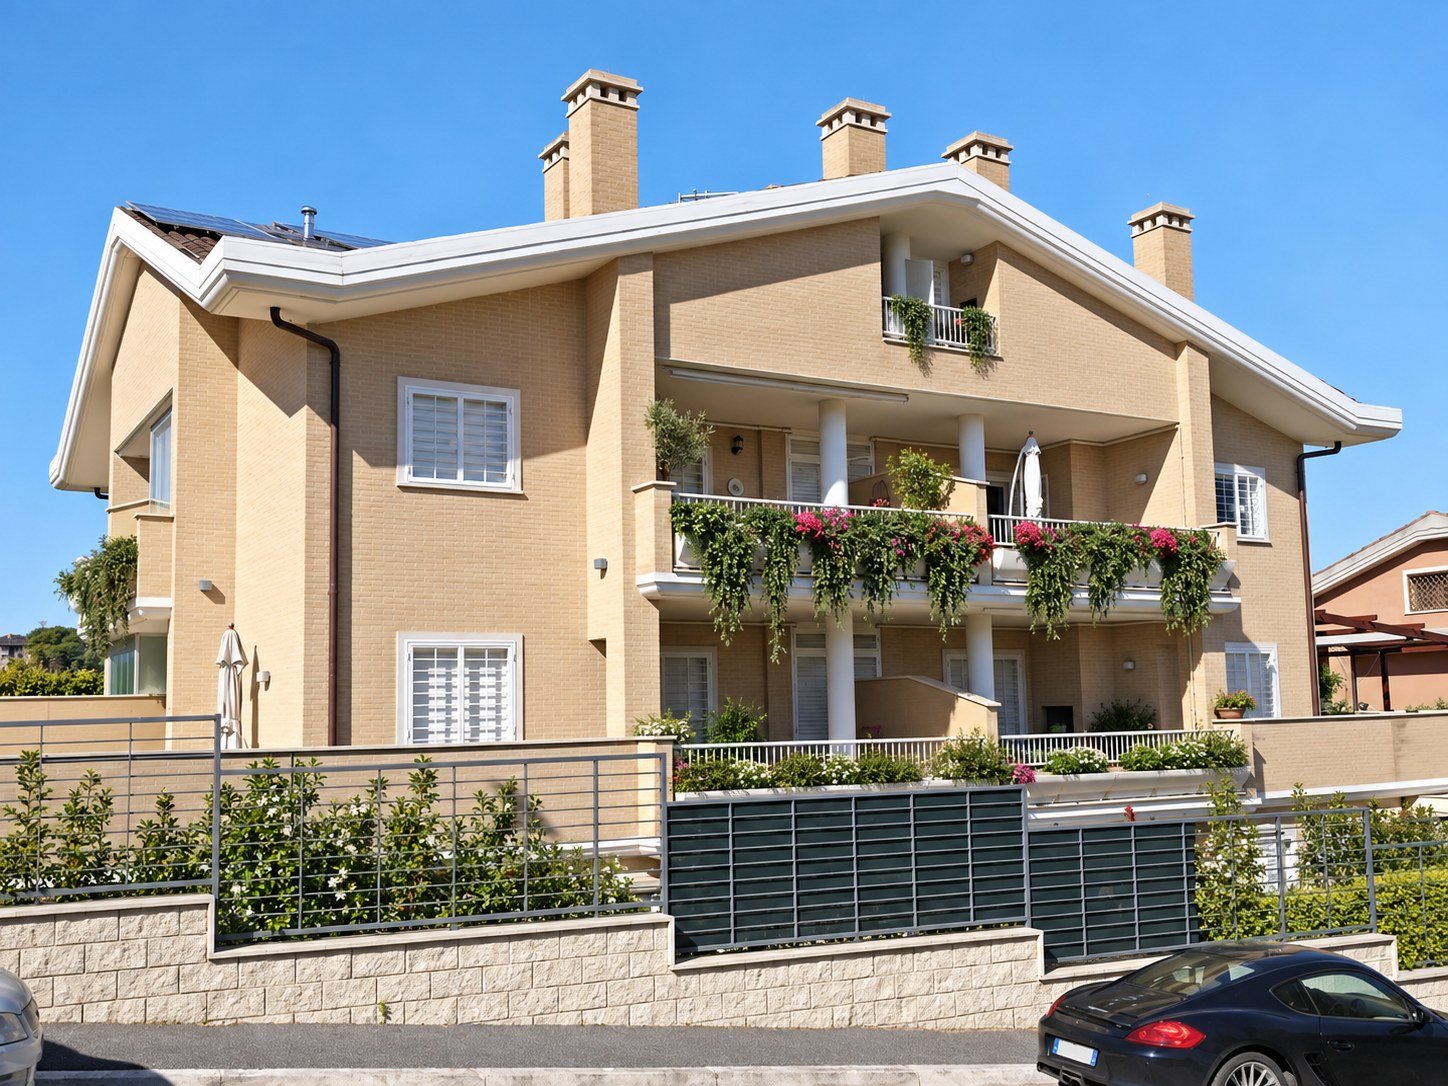
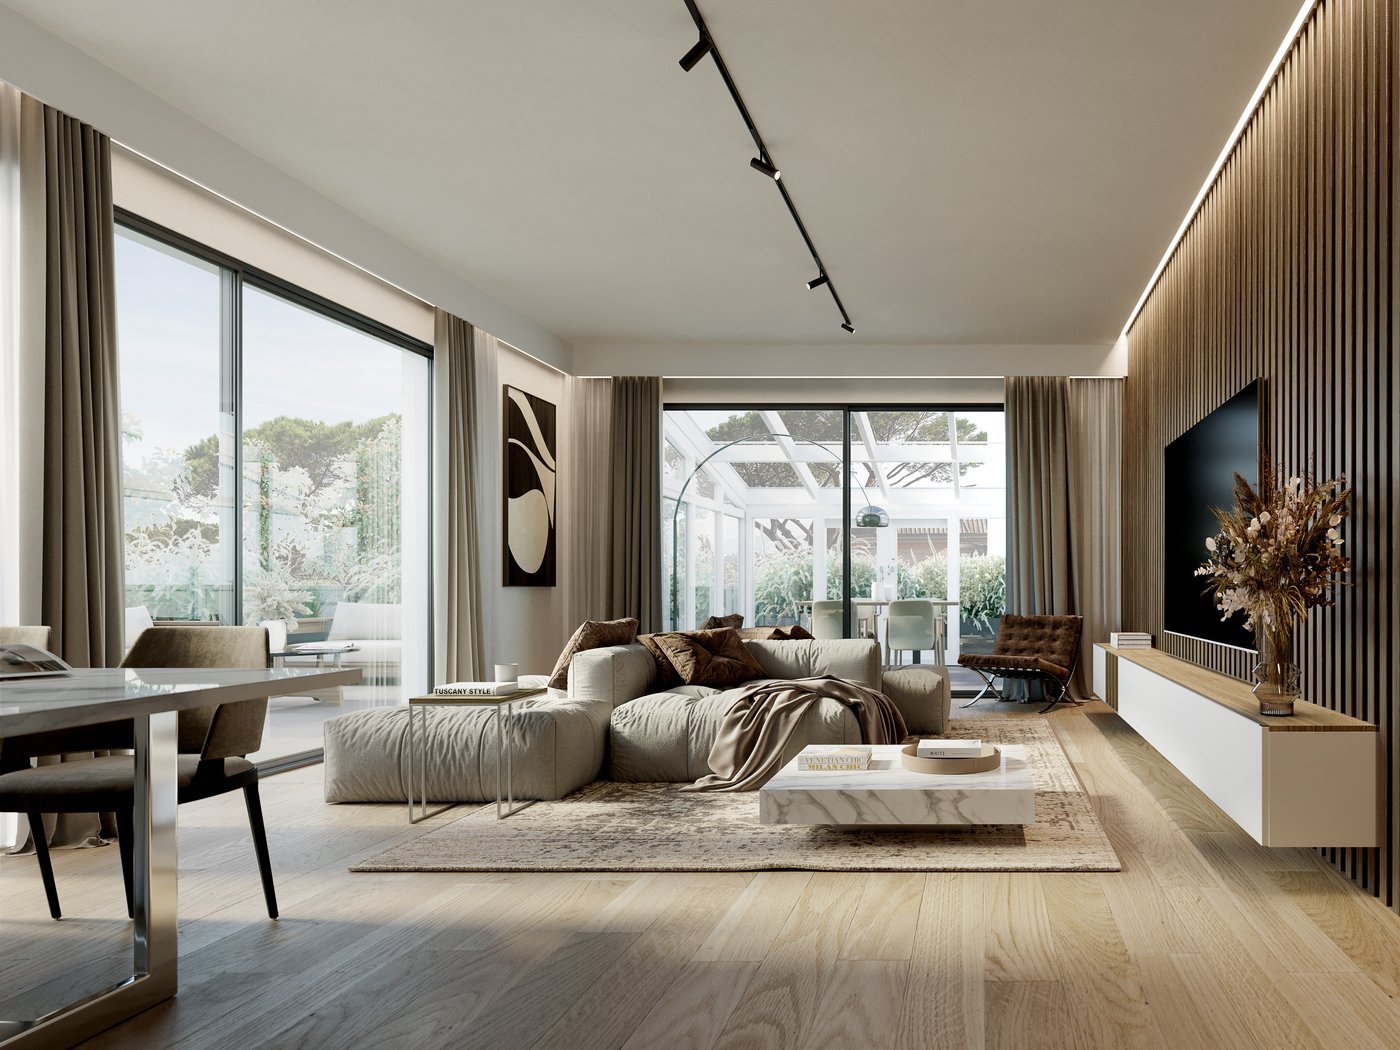
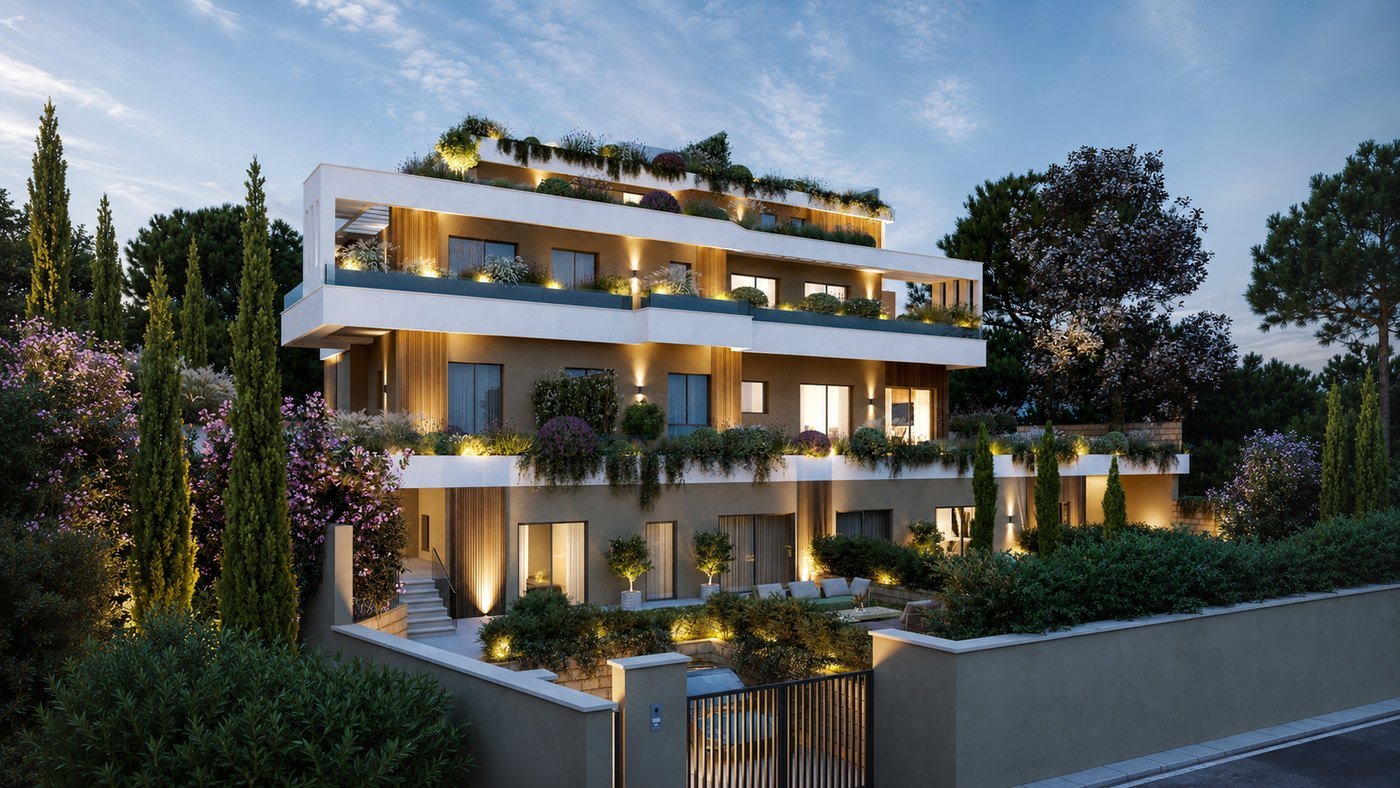
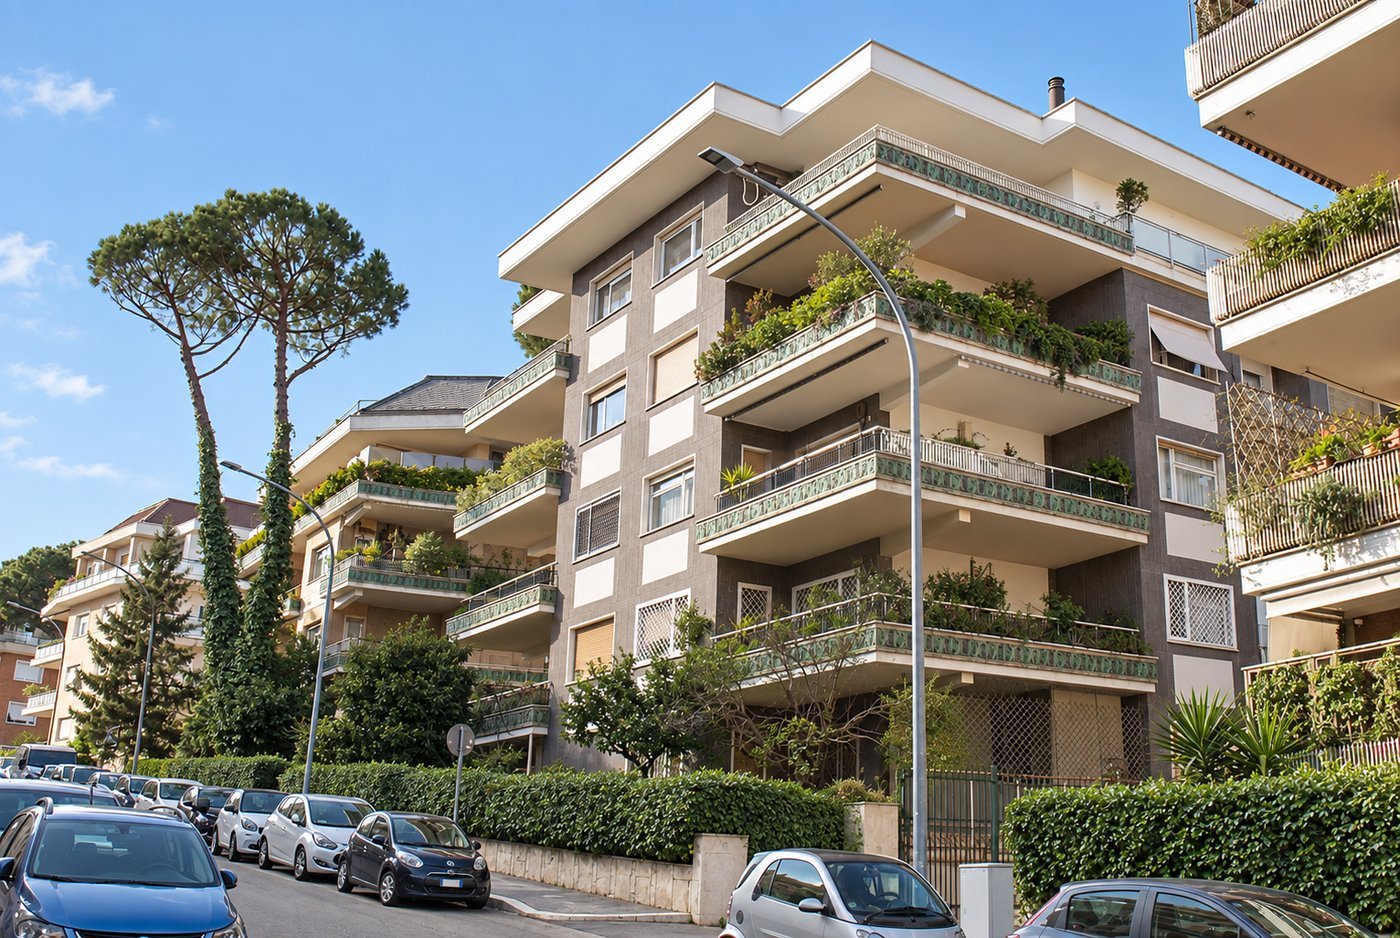
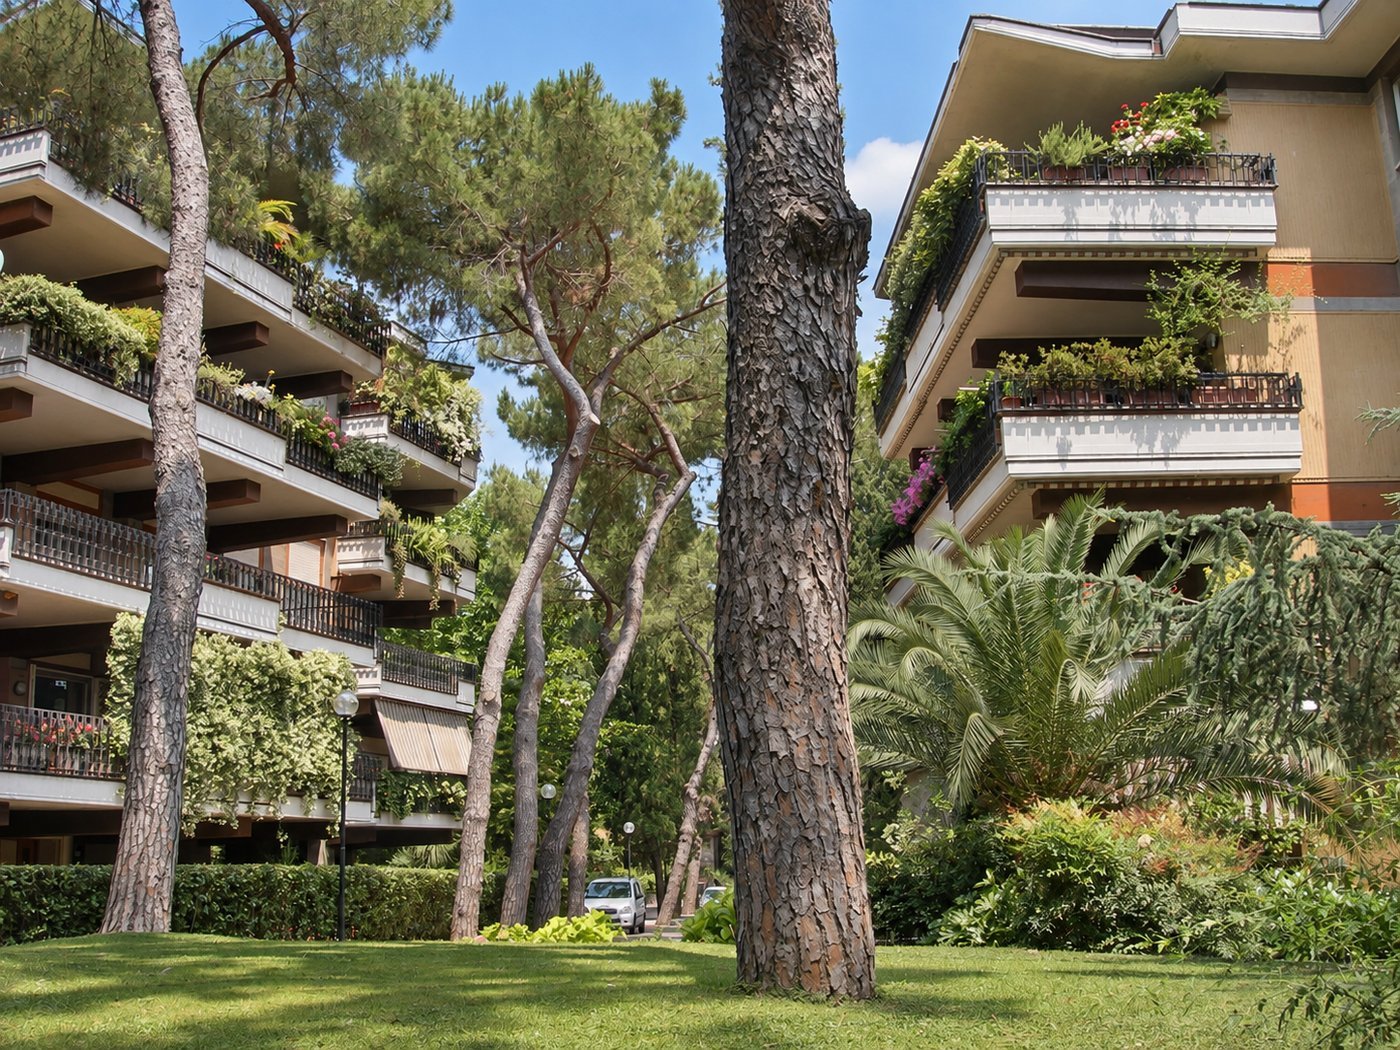
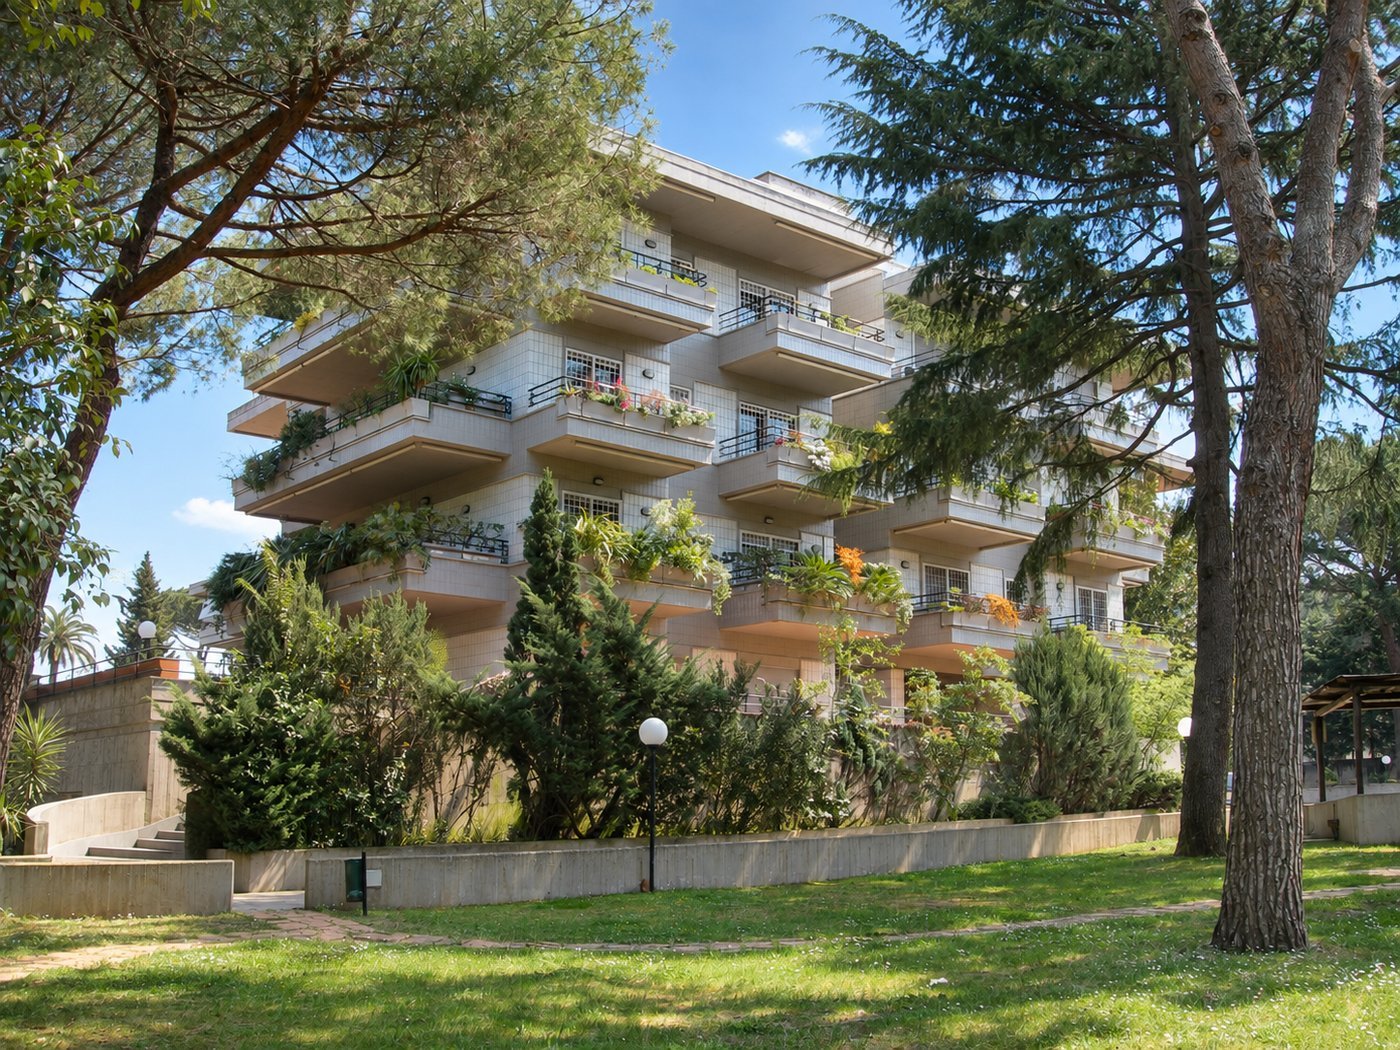
We acquire, redevelop, and add value to residential properties in the
prime areas of Rome. We build multistory parking garages and urban infrastructure as a general contractor. Through our advisory division, we support real estate developers, owners, and investors.
A century of construction in Rome
The operating brand for development
98
years of building in Rome
IV
generation at the helm
350,000+
sq m of sellable area developed
80+
real estate projects
The direct line of descent
One family, four generations at the helm
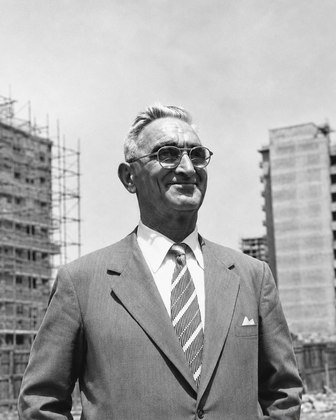
From Giuseppe Matteoni, born in 1889, to the present day, one Matteoni from each generation has led the Group: the same craft, handed down and refined for almost a century.
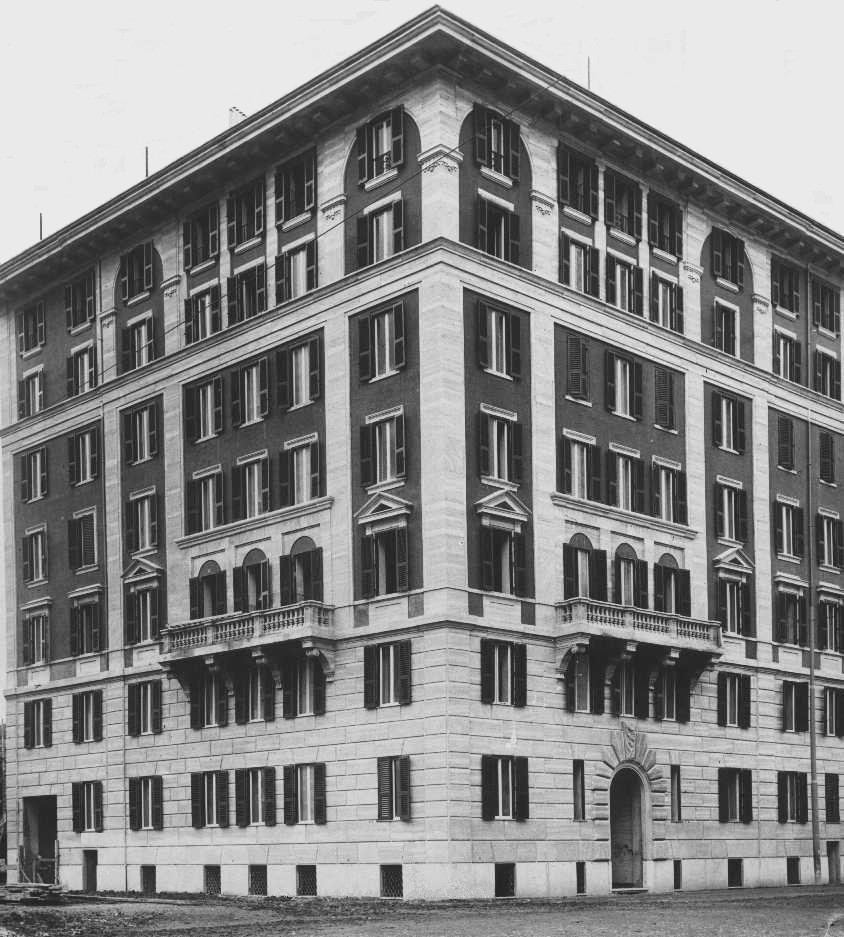
Giuseppe opened his first construction sites in Rome
in the late 1920s, in the Prati district, after the years in America that had given the
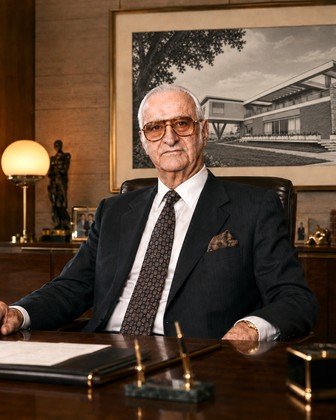
family capital and method. Aldo, born in 1923, lived through the postwar reconstruction and
the economic boom and put his name to the Group’s largest developments, from the entire San Godenzo district on the Cassia to
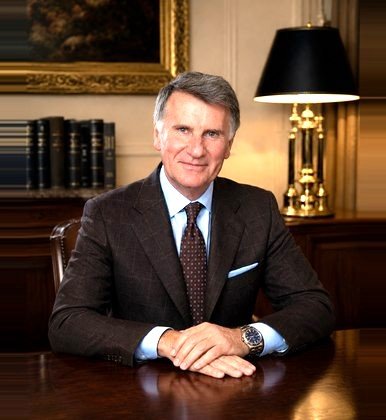
Parco dei Pini. Riccardo, born in 1953, consolidated the portfolio and steered the
Group toward urban parking and foreign markets. Lapo, born in 1986,
is now bringing the focus back to prime residential redevelopment, with financial
discipline and modern data-driven tools.
I
Giuseppe Matteoni
1889
The founder: from America to Rome, a story of courage and determination
II
Aldo Matteoni
1923
The boom years, the prime condominiums, and the major developments
III
Riccardo Matteoni
1953
The direction and consolidation of the Group along modern lines, and the expansion abroad
In Rome’s northern districts and semi-central areas, demand for carefully renovated properties remains strong, driven by the quality of the spaces, the light, and the views. Buyers favor move-in-ready homes, where building systems, finishes, and layout have already been thoughtfully redesigned: those buying at the high end are not looking for a renovation project to manage; they are looking for a finished home in keeping with its setting. The price gap between a property in need of renovation and a turnkey one continues to widen, rewarding those whose renovations rest on a well-conceived design.
Selective demand has a sorting effect on supply. Properties with flaws in their layout, exposure, or setting stay on the market longer and face tougher negotiations, while the right product (the right size, light, views, amenities) finds its buyer quickly and without concessions on price. It is a dynamic that rewards craft: reading a building before others do, understanding which flaws a redesign can correct and which it cannot, and walking away from projects where the flaws are structural.
The first factor remains location, but it must be read with precision. In prime areas value is not evenly distributed: it changes from one street to the next, from one side of the same street to the other, depending on quiet, greenery, orientation, and the services within walking distance. The micro-market matters more than the district, and the individual building more than the micro-market. This is why the valuation of a high-end property cannot be reduced to a price per square meter multiplied by the floor area.
The second factor is the quality of the work. An experienced buyer can tell a cosmetic renovation from a true redevelopment in a few minutes: new building systems, insulation, a layout redesigned for contemporary living, materials chosen to last. The difference does not show in photographs; it shows when one lives in the home, and it is the difference the high-end market pays for most readily.
The third factor is scarcity. Supply on prime streets is structurally limited: the number of buildings is fixed, large units are few, and those who own them rarely sell. When a well-executed redevelopment comes on the market, the window is short, and those who have been watching for some time know it. For sellers, this means that the right product needs no discounts; for buyers, that waiting for a price drop often means losing the opportunity.
Another element that the high-end market weighs more and more heavily is the building, not just the apartment. The condition of the common areas, the maintenance of the facades, the presence of a concierge, and the quality of the lobby and staircases count for more in valuations than they were given credit for in past years. A perfect apartment in a neglected building is hard to sell; a good apartment in a well-kept building sells well. For those who redevelop, this means thinking, where possible, in terms of the entire building or at least the common areas, because perceived value starts at the front door.
Finally, transparency. Buyers of high-end property in Rome are well informed, often advised by professionals, and compare what they see with what they are told. Documentation in order, verified zoning and cadastral compliance, clear specifications, and available certifications are not bureaucratic formalities: they are what allows a sale to close without discounts and without second thoughts. This, more than price, is what separates the properties that sell from those that sit on the market.
The reuse and redevelopment of the building stock remain the main way to regenerate cities without consuming new land. Planning rules increasingly reward work on existing buildings, with simplified procedures for those who renovate dated buildings and bring them up to code. For developers, this means concentrating expertise and capital where the city is already built, giving properties a new life. Rome, with its enormous stock of twentieth-century buildings, is one of the places where this strategy has the greatest potential.
The direction is now clear in the regulatory framework too. Limiting land consumption has become a permanent objective of land-use policy, and the implementing tools, from incentives for building replacement to simplified procedures for renovation, combine to make work on existing buildings more advantageous than new expansion. This is not a single rule but an approach that runs through municipal planning, building regulations, and the criteria lenders use to evaluate projects.
The price of this transition is complexity. Working on the built environment requires thorough condition assessments, tailor-made design, and construction sites that are harder to manage: surprises hide in the masonry, in the floor slabs, in the drain stacks, and in the layers of earlier work. Those who built their method on new construction find that renovation is a different craft, one that consists of inspections, probes, checks, and decisions made as the work proceeds, with the calm of those who already know what they may find.
And it is precisely this complexity that acts as a barrier to entry. Redevelopment cannot be improvised: it requires an archive of real cases, a network of skilled workers used to working inside occupied buildings, and an estimating skill that comes from experience, not from textbooks. Those with decades of work on twentieth-century buildings behind them start with an advantage that capital alone cannot buy, because capital can pay for the construction site but cannot buy the ability to read it.
For the city the result is twofold: buildings that become efficient and safe again without consuming a single square meter of new land, and districts that renew themselves from within, preserving the urban fabric and the quality of community life that made them sought after. For those working in the industry, renovation is no longer a niche but the main arena of competition, and craft once again counts more than scale.
To be worthy of the name, regeneration cannot stop at the individual unit. Working on the envelope, on centralized systems, on common areas, and on appurtenances means restoring value to the entire building and, with it, to its context. It is a more demanding approach than working apartment by apartment, but it is the only one that aligns the developer’s interest with that of the people who will live in the building in the years to come.
Then there is the question of building replacement: when the existing building cannot be salvaged because of its structure, layout, or performance, demolishing and rebuilding on the same footprint still counts as regeneration in every respect, because it consumes no new land and replaces an obsolete structure with an efficient one. Regional and municipal rules have recognized this for some time, and the choice between renovation and replacement must be made case by case, with an honest assessment of existing conditions. Regeneration is not a label: it is the choice, building by building, between what can be renovated and what is better rebuilt.
Data-driven analysis and predictive tools are becoming a source of competitive advantage across the entire real estate value chain, from property selection to pricing. Proprietary platforms cross-reference market data, construction costs, and time on market to estimate a project’s margin before the property is even acquired. Artificial intelligence does not replace craft, but amplifies it: it reduces valuation errors and frees up time for the decisions that matter. Those who were first to build these tools have a head start in a market where precision is what protects margins.
The decisive factor is not the tool but the data. Models and platforms are only as good as the historical data that feed them: without actual costs, actual timelines, and actual outcomes, even the most sophisticated algorithm produces elegant and wrong estimates. Those who have worked in the same market for generations have an archive that no public dataset can replicate, because public data show asking prices and area averages, not what actually happened on a construction site and in a negotiation.
The concrete applications are less spectacular and more useful than the current narrative suggests. In scouting, models filter hundreds of leads and flag for human review only the properties that meet the criteria for location, size, condition, and price. In feasibility analysis, they simulate cost, timing, and sales scenarios and show immediately how well a project holds up under conservative assumptions. On site, they keep accounting, progress, and suppliers aligned, flagging variances as they happen rather than after the fact.
Adoption in the sector is moving at two speeds. Large institutional players are investing in platforms and dedicated teams; the family businesses that make up most of the Italian market are looking on, often with skepticism. Those who belong to the second category but have moved like the first occupy a rare position today: they have firsthand knowledge of the local market and of the construction site, and at the same time the tools to read both with precision.
The limitation to keep in mind is that no model makes the decision for the person who signs. Technology helps people see sooner, make fewer mistakes, and devote their time to the choices that require judgment: which building to buy, at what price, and with what plan. The rest, if properly set up, can and should be entrusted to the machine.
An often overlooked aspect is data discipline. An intelligent infrastructure only works if every project, every invoice, every progress report enters the system once, in the same format, and remains linked to the rest: the single ledger is the prerequisite for every subsequent analysis. Building it requires less technology and more method, and for this reason the businesses that have always worked in an orderly way start with an advantage in this transition too.
One caveat remains: artificial intelligence is confidently wrong when data are scarce or skewed, and in the real estate market scarce data are the rule for micro-markets and for rare properties. In the high-end segment, where every building is a case unto itself, the model is an aid to judgment, never a substitute for it. Technology shortens the time it takes to decide; the responsibility for deciding remains undiminished.
Falling interest rates are rekindling demand for renovated properties in central areas, and selling times are getting shorter. Lower borrowing costs restore households’ purchasing power and once again make buying competitive with renting. Demand is concentrating on high-end existing homes that have already been redeveloped, where the buyer avoids the uncertainty of renovation work. For developers, this is the time to bring finished, well-positioned products to market, taking advantage of a window of renewed optimism.
The credit market confirms the picture: lending is recovering, banks are competitive on terms again, and mortgage demand is picking up, above all among buyers looking at quality existing homes in established areas. The effect on selling times is already visible in central micro-markets, where finished, well-priced products are moving quickly again. Negotiations are getting shorter, showings are turning into offers again, and the gap between asking price and sale price is narrowing.
Not all of the market benefits in the same way. Existing homes in need of renovation remain slower to sell, because on top of the price, the buyer has to take on a renovation whose timing and costs they do not control, and banks are more cautious about financing what is not finished. Product that has already been redeveloped, on the other hand, is easy to finance and sells better: this is why the gap between the two categories, rather than closing as rates fall, tends to persist.
The lesson of past cycles remains valid, however: windows of optimism reward those who prepared the product in advance, not those who improvise once the window has opened. A project started today to ride the moment will reach the market when conditions may have changed; a project set up prudently while the market was cold arrives ready when demand picks up again. The quality of execution, more than timing, separates the projects that finish well from those that stall halfway.
For buyers, the guidance mirrors that for sellers: falling rates do not lower high-end prices in established areas; they support them. Waiting for even better conditions makes sense only if the right property remains available, and on the most sought-after streets that rarely happens.
For developers who rely on debt financing, falling rates have a second effect, on the cost side: cheaper construction financing and margins that, with sale prices unchanged, have room to breathe again. Here too prudence remains the rule: a project that holds up only at low rates is a fragile project, and cycles have taught us that credit conditions change faster than buildings go up.
The overall message, for professionals and buyers alike, is to treat interest rates as one variable among several, not as the decisive one: the location, quality, and scarcity of the product remain the factors that determine value over time. The cost of borrowing changes the pace of the market, not the hierarchy of what holds value.
The arrival of services and infrastructure in Rome’s northern districts strengthens residential appeal and long-term values. New transit lines, school campuses, and retail space make these areas increasingly self-sufficient and livable. The residential market benefits directly: where the quality of daily life improves, demand firms up and prices find lasting support. Roma Nord, historically linked to our family’s name, remains an ideal vantage point for observing this trend.
In Rome, the geography of value moves slowly, but it does move. The districts that combine accessibility, schools, and neighborhood shops capture demand from families who leave the center but do not want to give up its quality of life. It is stable, largely nonspeculative demand, which supports values even in the cold phases of the cycle, because those who buy a home to live in do not resell it at the first shift in market sentiment.
The case of Roma Nord is instructive because the pattern has repeated itself for decades. The Cassia and Flaminia corridors grew in waves, each time around a new piece of infrastructure or a new service: first the roads and connections, then the schools, then the shopping and sports centers, and with them the residential districts that surround them. Those who built along these corridors saw value follow the opening of each new hub, with a lag of a few years.
For developers, the practical lesson is to choose the micro-markets where infrastructure is actually arriving, telling announcements apart from real construction. Planned public works change values when they open, not when they are announced, and years can pass between announcement and opening. Value follows what actually opens, not the renderings: those who buy on the announcement pay today for an uncertain benefit; those who buy once construction is under way pay a still reasonable price for a benefit close at hand.
Finally, there remains a factor that maps do not show: the quality of the existing built environment. In the northern districts, buildings of very different eras and quality coexist, and each new service rewards the buildings around it in proportion to their quality. This is where redevelopment finds its natural place: bringing properties that the neighborhood has outpaced back up to its level.
The area’s recent history confirms this. The established Cassia and Flaminia corridors have seen a network of schools, sports facilities, commercial hubs, and health services grow up over the years, a network that today allows many families to go about their day without crossing the city. Each new addition has strengthened the values of the surrounding micro-markets, with an effect that has stabilized over time rather than fading. Whoever buys in these areas today is also buying the services that will open tomorrow.
Redeveloping existing buildings reduces land consumption and emissions, making it the preferred route to sustainable development. A building retrofitted with insulation, efficient systems, and renewable energy sources can achieve performance close to that of new construction, with a much lower environmental impact. European regulations push in this direction, linking incentives and property values to the energy rating. For developers, sustainability is no longer a cost but a factor that protects and increases value over time.
The European trajectory is set: the least efficient building stock will progressively lose appeal and bankability, while the energy rating now figures in banks’ loan underwriting alongside location and state of repair. The value differential between efficient and inefficient properties, already observable in transactions, is bound to widen, because at some point energy performance stops being a selling point and becomes a requirement.
The comparison with new construction must be made honestly. Building from scratch delivers excellent performance but carries an environmental cost that is rarely counted: demolition, disposal, the production of new structural materials, and land consumption. Deep renovation starts from a structure that already exists and concentrates the work where the benefit is greatest: the envelope, windows and doors, building systems, and renewable energy generation. When the result for residents is the same, the overall balance tips clearly toward renovation.
For owners and buyers alike, the question is a practical one. An efficient property costs less to run every month, is financed on better terms, and resells more easily, because the market has learned to read the energy rating as shorthand for the quality of the renovation. An inefficient property, by contrast, carries a double cost: the utility bills and the discount the buyer will demand as compensation for future work.
The deep renovation of existing buildings thus remains the route with the best balance of cost, time, and results: upgrades to the envelope, systems, and windows transform a twentieth-century building into a contemporary product, without the environmental cost of demolition and reconstruction and with a value that the market recognizes ever more explicitly.
Timing is a practical concern. Work on the envelope and systems requires a carefully organized construction site, especially when the building remains occupied during construction: the sequencing of the work, access management, and communication with residents make the difference between a project that runs smoothly and one that drags on. Those with experience running construction sites in occupied buildings start with an advantage that design alone does not guarantee. Efficiency, in the end, is not a technical matter: it is the most concrete way to protect a property’s value over time.
Services
Solutions for real estate operators, owners, and investors
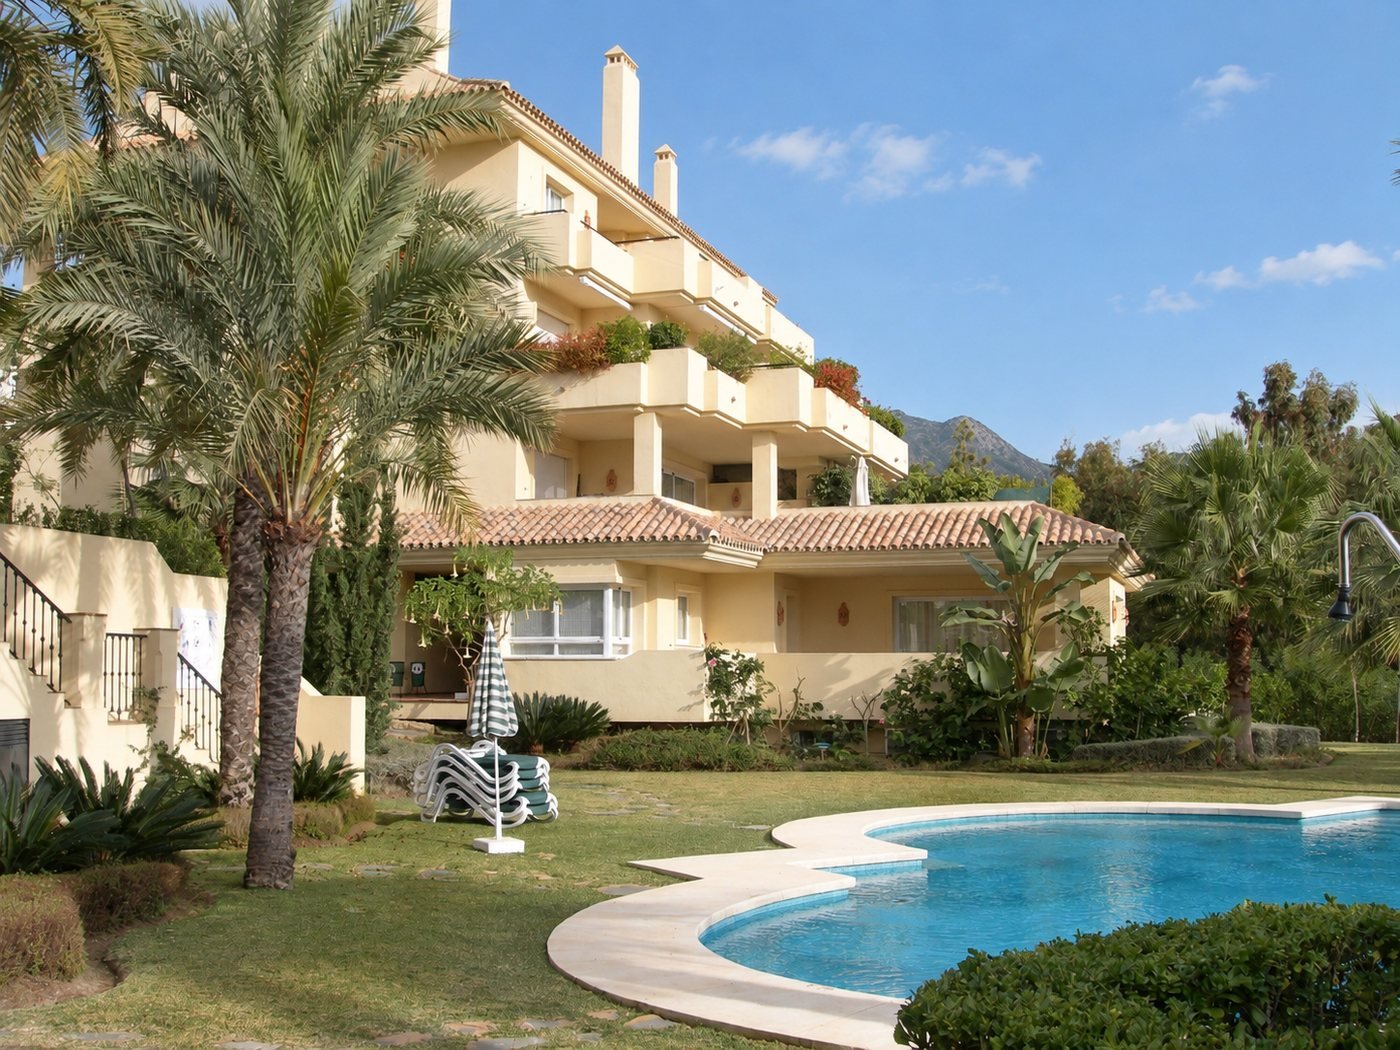
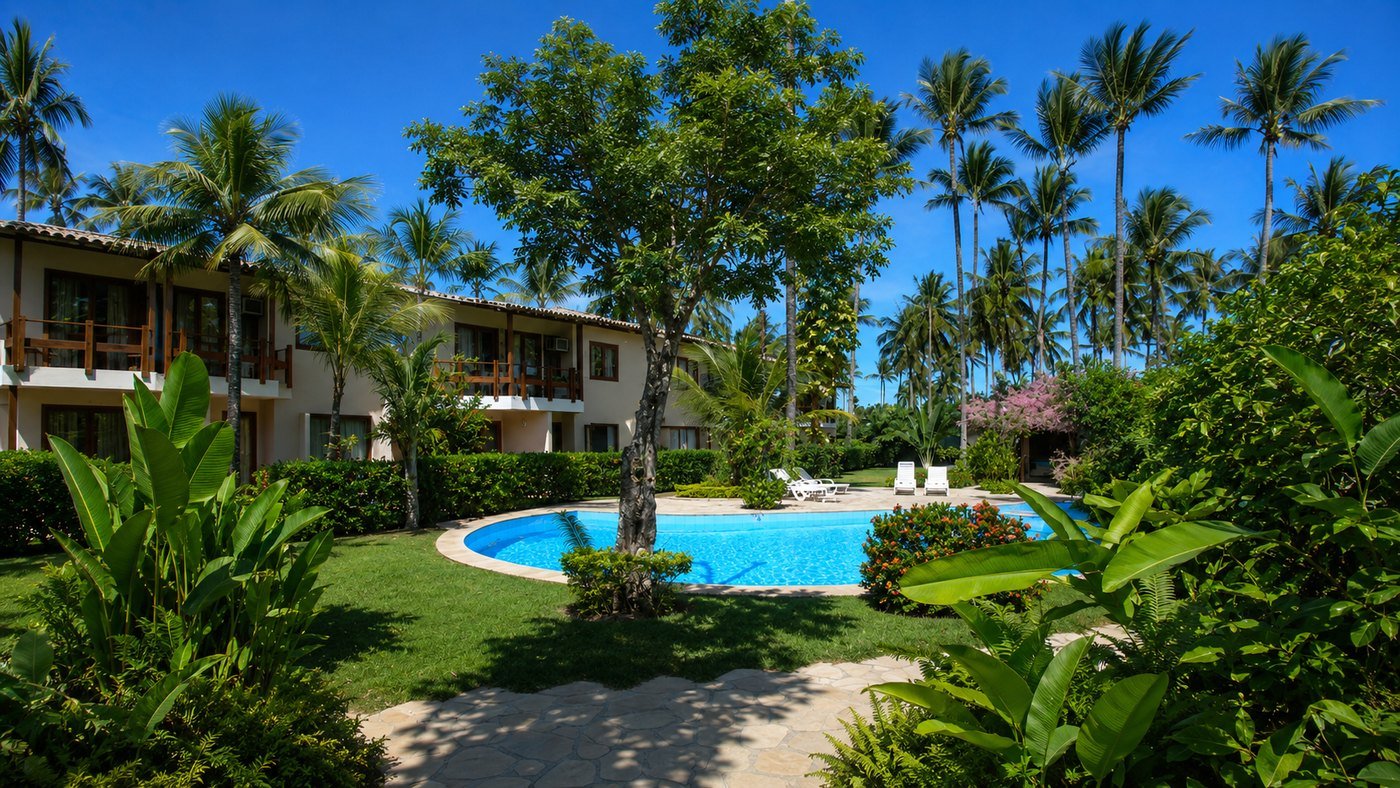
Le Farfalle - Roma NordLe Farfalle - Roma NordPoggio delle Rose - Roma NordLas Mariposas - Marbella, SpainFlaminia - Roma NordLe Farfalle - Roma NordVilla Aurora - Porto Seguro, BrazilParco dei Pini - Roma NordVilla Lucy - Roma Nord
The Group’s companies
Case di Roma Group S.r.l.
CdR - Promozione e Sviluppo S.r.l.
CdR - Sviluppo e Valore S.r.l.
We respect your privacy
We use necessary cookies and technologies and, subject to your consent, tools for statistics, experience analysis, marketing, and external content. You can accept all, reject all, or customize your choices at any time. Learn more in the Cookie Policy.
NecessaryAlways active
Essential for browsing and for remembering your choices.
Statistics
They help us understand how the site is used, in aggregate form.
Planned tools: web analytics for traffic and performance - provider, purpose, and duration shown in this panel upon activation.
Experience analysis
Heatmaps and session recordings in masked form, to improve the user experience.
Planned tools: heatmaps and session recording with full masking of forms - provider and duration shown upon activation.
Marketing
For personalized content and campaigns.
Planned tools: conversion measurement and remarketing - provider and duration shown upon activation.
External content
Embedded third-party content, such as Google Maps: it loads only after your consent.
Tools: Google Maps (provider: Google Ireland Limited) - map on the Contact page, loaded only after consent to this category.
׋
›
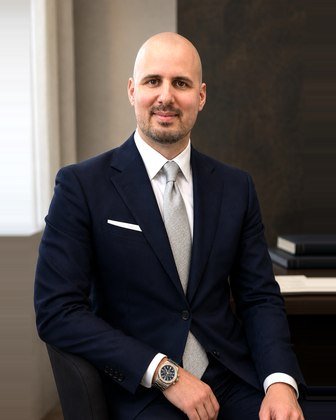
Lapo MatteoniCEO, Gruppo Matteoni - Case di RomaLinkedIn profile